

Firmer inflation, crude near $100 and a rupee around 96 to the dollar ended a four-meeting pause. August CPI was 4.82%, Q1 FY27 GDP grew 7.8%, and most economists had already priced a 25 bps hike, with some seeing the repo moving toward 5.75–6% by the end of FY27.
BY PC Bureau
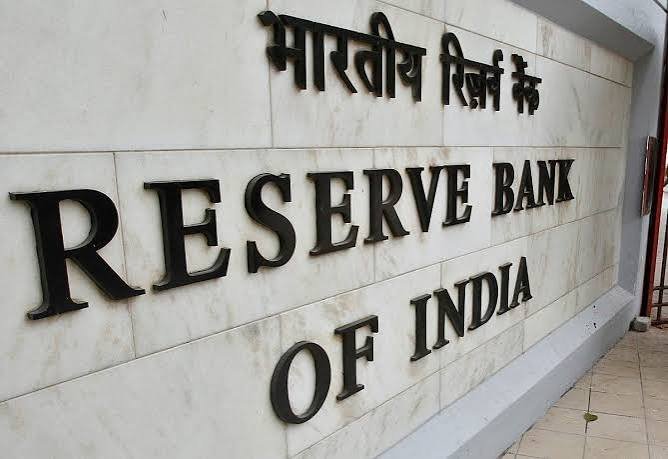
October 7: The Reserve Bank of India’s Monetary Policy Committee has raised the policy repo rate by 25 basis points to 5.50%, the first increase in nearly four years, as inflation pressures rebuild.
RBI Governor Sanjay Malhotra announced the outcome of the October 5–7 meeting this morning. Early market reports also indicate the stance has shifted from neutral to calibrated tightening. A press conference is scheduled for noon.
Malhotra said the decision reflected a less favourable inflation outlook, although the Indian economy continued to show resilience.
“Inflation and its outlook are not as benign as they were last year,” Malhotra said. Headline CPI inflation is expected to average around 5.8% over the next three quarters, while inflation for the full financial year is projected at 4.4%.
READ: Missing Posters Outside Premanand Maharaj Ashram as Families Search for Relatives
What changed
The repo rate is the rate at which the RBI lends overnight funds to banks. It was held at 5.25% through four consecutive reviews in 2026 (February, April, June and August), after the MPC cut it by 25 bps in December 2025.
That pause followed a 125 bps easing cycle in 2025:
- February 2025: cut to 6.25%
- April 2025: cut to 6.00%
- June 2025: cut to 5.50%
- December 2025: cut to 5.25%
A move to 5.50% reverses the last of those cuts and is the first hike since February 2023, when the rate was raised to 6.50% at the end of the previous tightening cycle. With the repo at 5.50%, the standing deposit facility rate would normally move to 5.25% and the marginal standing facility rate and bank rate to 5.75%.
Why the MPC turned
The backdrop has shifted since the August hold. August retail inflation was 4.82%, up from the very low prints of late 2025, and economists expect it to move above 5% in FY27. Crude has been elevated near or above $100 a barrel amid West Asia tensions, the rupee has weakened toward the mid-96s per dollar, and US yields have risen, with the 10-year near multi-year highs. Growth has not softened: Q1 FY27 GDP grew 7.8%, above the RBI’s earlier projection, which gives the MPC room to tighten without an immediate growth scare.
Polls ahead of the meeting were heavily one-sided. An Economic Times survey found 20 of 21 economists and bankers expecting a 25 bps hike; a Reuters poll put the share near 60%. Houses such as Crisil, HSBC, Axis and Morgan Stanley had pencilled in the start of a shallow tightening cycle, with some seeing another 50–75 bps by the end of FY27 and the repo possibly toward 5.75–6%.
What it means
For borrowers, external benchmark-linked home, auto and MSME loans reprice quickly, so EMIs are likely to rise as banks pass the hike through. Fixed-deposit and savings rates should edge up, though transmission on deposits has been slower than on loans in the last cycle. Bond yields, already nervous around 7.2% on the 10-year, will take their cue from the inflation forecast and whether Malhotra signals further hikes in December. Equity markets opened weaker ahead of the decision, with banks and autos under pressure.
The noon press conference should clarify the revised CPI and GDP projections and how firmly the committee is committed to further tightening.